Personal Services Business: The Tax Trap for Incorporated Consultants

Independent consultant working on a laptop at a desk

Personal Services Business: The Tax Trap for Incorporated Consultants

Independent consultant working on a laptop at a desk
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

What Is a Personal Services Business?

Incorporating is popular with consultants, IT contractors and other professionals who work for a small number of clients. The low small business tax rate is attractive. But if, without the corporation, you would really be the client’s employee, the CRA can treat the company as a personal services business (PSB), and the tax result is far worse than if you had never incorporated.

This guide explains what a PSB is, how the CRA decides, what it costs and how to reduce the risk. It is part of our guide to bookkeeping for consultants and professional services.

Consultant working from a home office desk

What Makes a Corporation a PSB

The rule targets an “incorporated employee”. A corporation is carrying on a personal services business when it provides services to a client through an individual who owns 10% or more of the corporation (directly or with related people), and that individual would reasonably be regarded as the client’s employee if the corporation were not there.

The CRA uses the same factors it uses to decide employee versus contractor:

  • Control: does the client decide how, when and where the work is done?
  • Tools and equipment: who provides the laptop, software, office and phone?
  • Chance of profit, risk of loss: is your income fixed hourly with no real business risk?
  • Integration: do you work like staff, with a company email, a seat in team meetings and no other clients?

A long-term contract with one client, set hours, the client’s equipment and supervision by the client’s managers looks very much like employment, regardless of what the contract says.

What a PSB Designation Costs

A PSB does not get the small business deduction or the general corporate rate reduction, and pays an extra 5% federal tax. The federal rate on PSB income is 33%, and with Ontario’s 11.5% general rate the combined rate is about 44.5%, compared with about 12.2% for an active small business. Dividends paid out later are then taxed again personally.

Deductions are also restricted. A PSB can generally deduct only the salary, wages and benefits paid to the incorporated employee, costs of negotiating contracts, and legal costs of collecting amounts owed. Rent, software, travel and other normal business expenses are largely disallowed.

The result is often more tax than if the person had been an employee. And PSB reassessments usually reach back several years, with interest.

Exceptions to the PSB Rules

A corporation is not a PSB if:

  • it employs more than five full-time employees throughout the year in the business; or
  • the services are provided to an associated corporation.

Most one-person consulting corporations cannot use either exception, so for them the question comes down to whether the working relationship really is independent.

How Consultants Reduce the Risk

There is no form that makes you safe, but the facts can be made stronger:

  • Work for more than one client, or at least market your services and be able to show it.
  • Use a written contract that reflects independence: deliverables or project fees rather than open-ended hours, your right to set your own methods and schedule, and the right to subcontract.
  • Provide your own equipment, software and workspace, and carry your own insurance.
  • Bear real business risk: fixed-price work, your own costs, invoices that look like a business’s invoices.
  • Avoid the trappings of employment: client email addresses, staff ID, performance reviews, vacation approvals.

Paying yourself mostly through salary also limits the damage, because salary remains deductible even if the corporation is later found to be a PSB. Our guide to tax planning for owner-managers and the salary vs dividend calculator help you set the mix.

When PSB Risk Is Highest

Reassessments often follow a predictable path: a contractor works exclusively for one client through an agency for years, the engagement ends, and either the worker claims EI or the CRA reviews the client. IT contractors, project managers and former employees who return as consultants are frequent targets.

If your situation looks like employment, it is better to know before filing. The corporation’s year-end planning, covered in our T2 corporate tax guide, is the right moment to review it.

Not Sure Whether Your Corporation Is at Risk?

We review consultants’ contracts and working arrangements, set up salary and dividend plans, and prepare the corporate return. See our corporate tax services or get in touch.

Book a consultation →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
Rental Property Expenses in Canada: What You Can Deduct on Form T776

Landlord holding the keys to a rental property

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Landlord holding the keys to a rental property
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

Rental Property Expenses: Every Dollar Counts

Rental properties rarely throw off much cash once the mortgage is paid, so the tax deductions matter. Claim too little and you overpay every year. Claim the wrong things, such as an improvement as a repair or your own labour, and a CRA review can take back several years of deductions with interest.

Rental income and expenses are reported on Form T776, and the CRA’s Rental Income guide (T4036) sets out the rules. This guide translates them into a practical checklist. It is part of our guide to bookkeeping for real estate agents and investors in Canada.

Model house and keys on a table representing a rental property

Rental Expenses You Can Deduct on Form T776

These are the common current expenses on the T776:

ExpenseNotes
Mortgage and loan interestInterest only, on money borrowed to buy or improve the rental. Principal is not deductible.
Property taxesFor the period the property was available for rent.
InsuranceThe current year’s premium. Prepaid future years are deducted in those years.
Repairs and maintenanceLabour and materials to restore the property, not improve it.
UtilitiesOnly if you, not the tenant, pay them.
Condo feesYour share of common-property costs.
Management and professional feesProperty managers, legal fees for leases and collecting rent, accounting.
AdvertisingListings and finder’s fees for tenants.
WagesPaid to a superintendent or maintenance staff, not to yourself.
Motor vehicleLimited: with one property, only when you do repairs yourself and carry tools or materials.

Repairs vs Improvements on a Rental Property

This is where most landlords get into trouble. A current expense keeps the property in the condition it was in. A capital expense gives a lasting benefit or improves it beyond its original condition.

  • Repainting, fixing a leaking roof, replacing a broken window pane: current.
  • A new addition, upgrading wooden steps to concrete, a full renovation before renting: capital.
  • Replacing a whole roof or a furnace: it depends. A like-for-like replacement that only restores the property can be current, while an upgrade or a part that extends the building’s life is usually capital. Get advice before claiming large items.

Keep invoices that describe the work clearly. “Repairs, $18,000” invites questions; “replace damaged drywall and repaint unit 2 after tenant move-out” usually does not.

Capital Cost Allowance on a Rental Building

You cannot deduct the cost of the building in the year you buy it. Instead you claim capital cost allowance (CCA) each year. Most residential buildings fall into Class 1 at 4% a year on a declining balance, and a separate class is generally required for each rental building that cost $50,000 or more.

When you buy, split the price between land and building, because land is never depreciable. Property tax assessments are a common basis for the split.

Three rules to remember:

  • CCA cannot create or increase a rental loss. You can only claim it against net rental income.
  • CCA is optional. Many owners claim less in low-income years, because CCA claimed is recaptured as income when you sell for more than the remaining undepreciated cost.
  • In the year you buy, the half-year rule usually applies, although accelerated investment incentive rules can change the first-year amount.

Renting Part of Your Home and Other Special Cases

If you rent a basement suite or a room, you can deduct the share of expenses that relates to the rented area, usually based on square footage or number of rooms. You cannot claim the personal share, and you generally should not claim CCA on the part of your home you live in, because it can affect the principal residence exemption.

A few other rules to know:

  • Vacant land: interest and property taxes are limited to the rental income from the land and cannot create a loss.
  • Short-term rentals: expenses for short-term rentals that do not comply with provincial or municipal licensing or zoning rules are no longer deductible for the non-compliant period.
  • Co-owned properties: income and expenses are split by ownership share, and each owner reports their share on their own T776.

Rental Property Records That Hold Up in a CRA Review

Keep a separate bank account for each rental property, or at least for your rentals as a group, and keep receipts, leases and mortgage statements for six years. A simple ledger or bookkeeping file per property makes the T776 a matter of copying totals rather than reconstructing a year.

The rental schedule is filed with your personal return, due 30 April. Our tax filing calendar covers the deadlines, and our bookkeeping services can keep each property’s books for you.

Want Your Rental Books and T776 Done Right?

We keep property-level books for landlords and investors, separate repairs from improvements, track CCA by property and prepare the rental schedules at tax time. Get in touch to talk about your portfolio.

Book a consultation →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Modern dental office with treatment chair and equipment

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Modern dental office with treatment chair and equipment
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

Incorporating a Dental Practice: A Tax Deferral, Not a Tax Cut

Almost every dentist is told at some point that they should incorporate. Sometimes that is good advice and sometimes it just adds a second set of filings. A dental professional corporation lets you earn practice income inside a company taxed at a low small business rate, and leave what you do not need personally to grow there. Whether it pays depends on how much of your income you can afford to leave in the corporation.

This guide covers how dental professional corporations work in Ontario, who can own the shares, the tax mechanics, what changed for income splitting, and the costs. It is part of our guide to dental bookkeeping and accounting.

Bright dental treatment room in a private practice

How a Dental Professional Corporation Works

A dental professional corporation is an ordinary Ontario corporation with extra conditions. Under Ontario Regulation 39/02, each voting share must be legally and beneficially owned by a member of the Royal College of Dental Surgeons of Ontario. Non-voting shares can be owned by another member, by a family member of a voting dentist shareholder (their spouse, child or parent), or in trust for the dentist’s minor children.

The corporation’s name must identify it as a professional corporation, and it must obtain a certificate of authorization from the RCDSO before practising through it. The corporation then bills patients and insurers, pays staff and expenses, and pays you a salary, dividends or both.

Incorporating does not limit your liability for your own professional work. It can limit liability for some business obligations such as leases, but you still need malpractice coverage.

The Tax Advantage of a Dental Professional Corporation

A Canadian-controlled private corporation pays tax at the small business rate on the first $500,000 of active business income: 9% federally plus 3.2% in Ontario, about 12.2% combined. A dentist earning the same income personally pays graduated rates that reach 53.53% in Ontario.

The difference is a deferral, not a permanent saving. When you take money out as dividends, personal tax applies, and the system is designed so the combined tax ends up roughly similar. The benefit comes from leaving money in the corporation for years, investing it with pre-tax dollars and choosing when to draw it, for example in lower-income years or retirement.

If you spend everything the practice earns, the deferral is small and may not cover the extra costs. If you can regularly leave a meaningful amount in the corporation each year, it usually pays. Our salary vs dividend calculator and salary vs dividends worked example show how the mix of pay affects the result.

Income Splitting After the TOSI Rules

Before 2018, many dentists issued non-voting shares to a spouse or adult children and paid them dividends taxed at their lower rates. The tax on split income (TOSI) rules now tax most of those dividends at the top personal rate.

Some exceptions still apply. Dividends to a spouse are generally excluded once the dentist is 65 or older. Family members who work in the practice on a regular, continuous and substantial basis (generally at least 20 hours a week) can also be excluded. The “excluded shares” exception that helps other businesses is not available to professional corporations.

Paying a reasonable salary to a spouse or child who works in the practice, for example in reception or the business office, is still fully allowed.

Passive Income and the Small Business Limit

Money left in the corporation is usually invested, and investment income has its own rules. Once the corporation’s passive investment income goes above $50,000 a year, its small business limit starts to shrink by $5 for every $1 over, and it disappears at $150,000. That pushes practice income onto the higher general corporate rate.

This only bites for dentists with large investment portfolios inside the corporation, but it is worth planning for with corporate-owned insurance, an individual pension plan or the timing of capital gains.

HST, Costs and When a Dentist Should Incorporate

Most dental services are exempt from GST/HST, so a dental practice does not charge HST on its services and cannot claim back the HST it pays on equipment, supplies and rent. That is true whether or not you incorporate, so HST is not a reason to incorporate either way.

The costs are real: legal fees to incorporate and obtain the certificate, an annual corporate tax return and financial statements, payroll for your own salary, and more bookkeeping. Associates can incorporate too, but the numbers need to work for their own income level.

Signs it is time: steady practice income well above what you spend, a plan to buy or expand a practice, or a desire to build savings inside the company. Our guide to the T2 corporate tax return covers the annual filing, and tax planning for owner-managers covers how to pay yourself.

Thinking About Incorporating Your Practice?

We model the numbers for your practice before you incorporate, then handle the corporate tax, payroll and bookkeeping afterwards. See our corporate tax services or get in touch.

Book a consultation →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
Tips and Gratuities in Canada: Payroll Rules for Restaurant Owners

Customer paying by card at a cafe payment terminal

Tips and Gratuities in Canada: Payroll Rules for Restaurant Owners

Customer paying by card at a cafe payment terminal
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

Who Controls the Tip Decides the Payroll Treatment

Tips are a large part of what restaurant staff take home, and they come with more rules than most owners realise. Whether you have to deduct CPP, EI and income tax depends on one question: does the employer control the tip? Provincial employment law then limits what you can do with tips at all, including how a tip pool works and whether you can share in it.

Getting this wrong means either under-deducting payroll and owing the CRA, or treating staff tips as your revenue. This guide covers the CRA rules, Ontario’s employment standards and the bookkeeping. It is part of our guide to restaurant bookkeeping and accounting in Canada.

Server holding a point-of-sale terminal while a customer pays by card

Controlled Tips vs Direct Tips

The CRA splits tips into two kinds, and the payroll treatment follows from that split. The CRA’s guidance defines controlled tips as tips the employer controls or possesses and then must pay to the employee.

Controlled tips (through payroll)Direct tips (not through payroll)
Mandatory service charges added to the billCash left on the table and kept by the server
Tips deposited into the employer’s bank account and paid out laterTips handed directly to staff
Tip pools where the employer sets the sharing formulaTip pools run and shared by employees themselves
Tips calculated as a percentage of sales by the employerCard tips returned to the employee in full, in cash, at the end of the shift

The test is about control, not payment method. A card tip can be a direct tip if it is handed back in full and the employer has no say over it, and a cash tip becomes controlled once it goes into an employer-run pool.

How Tips Go Through Payroll: CPP, EI and Tax

Controlled tips are treated as employment income. You deduct CPP contributions, EI premiums and income tax on them, remit those deductions with the rest of your payroll, and report the tips in box 14 of the employee’s T4 along with their wages. They also count as insurable earnings on a Record of Employment.

Direct tips are still taxable income for the employee, but you do not deduct anything on them. The employee reports them on line 10400 of their return and can choose to contribute to CPP on them using form CPT20.

Because controlled tips increase each pay’s deductions, remember them when you calculate what to send the CRA. Our guides to payroll remittance in Canada and how to do payroll in Canada cover the mechanics.

Ontario Rules on Tips and Tip Pools

Ontario’s Employment Standards Act protects employee tips. An employer cannot withhold tips or make deductions from them, except:

  • deductions required by law, such as income tax, CPP and EI on controlled tips;
  • deductions ordered by a court;
  • amounts redistributed to other employees under a tip-sharing (tip pool) arrangement.

The employer can decide who shares in a tip pool and how it is split, without employees’ consent. Owners, partners, directors and shareholders can share only if they regularly perform, to a substantial degree, the same work as some or all of the employees who share in the pool. Ontario also allows a limited deduction for credit card processing fees on tips (not debit), and requires employers with a written tip-sharing policy to keep a copy for three years after it stops being used.

Under the ESA, tips are not wages, so they do not count toward minimum wage. Other provinces have their own rules, so check the employment standards where you operate.

Sales Tax and Service Charges

A voluntary tip is not part of the price of the meal, so no GST/HST applies to it. A mandatory service charge, such as an automatic gratuity on large tables, is part of what the customer must pay, so it is generally subject to GST/HST. It is also a controlled tip when it is paid out to staff. Our GST/HST guide covers how to report it.

Recording Tips in Your Books

When customers add tips to card payments, that money lands in your bank account, but it is not yours. Record card tips to a tips payable liability account, not to sales. When you pay them out, through payroll or in cash, the liability goes back to zero. Reconcile the account every pay period: a balance that grows means tips are being collected but not paid out, which is exactly what an employment standards complaint looks for.

Keep the tip-sharing policy, the daily tip reports from your POS and the payout records together. They are your evidence if staff, the CRA or the Ministry of Labour ask questions.

Want Tips Handled Correctly Every Pay Run?

We run payroll for restaurants, including controlled tips, remittances and T4s, and keep the tips liability reconciled in your books. See our payroll services or get in touch.

Book a consultation →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
How to Reconcile Shopify Payouts in Your Books: A Guide for Canadian Sellers

Online store owner checking an order package next to a laptop

How to Reconcile Shopify Payouts in Your Books: A Guide for Canadian Sellers

Online store owner checking an order package next to a laptop
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

Why Shopify Payouts Never Match the Sales Report

Every Shopify seller hits the same wall. The sales report says one number, the bank deposit says another, and the gap is made up of refunds, processing fees, chargebacks, sales tax and timing. If you record each deposit as sales, your revenue is understated, your fees disappear and your GST/HST return is built on the wrong figures.

The fix is a standard bookkeeping method called a clearing account. It takes a little setup and then works the same way every payout. This guide walks through it with a worked example. It is part of our guide to ecommerce bookkeeping in Canada.

Ecommerce seller packing an order box at a workspace

What Is in a Shopify Payout

Open any payout in Shopify and you will see it is built from several pieces:

  • Gross sales for the orders included, after discounts.
  • Shipping you charged customers.
  • Sales tax collected, which depends on where each customer is.
  • Refunds, including the tax and shipping refunded.
  • Processing fees deducted by Shopify Payments.
  • Chargebacks, dispute fees and reserves, if any.
  • Adjustments, such as reversed disputes or currency differences.

Payouts also lag behind orders by a few business days, so a sale on 30 June can arrive in July. That timing difference is another reason deposits and sales reports never line up month by month.

The Clearing Account Method, Step by Step

Create a current asset account called Shopify Clearing. Think of it as money Shopify is holding for you. Then, for each payout (or each day of sales):

  1. Record the sale: debit Shopify Clearing for the total charged to customers, and credit sales, shipping income and sales tax payable.
  2. Record refunds: debit sales returns and sales tax payable, credit Shopify Clearing.
  3. Record fees: debit merchant fees expense, credit Shopify Clearing.
  4. Record the deposit: debit the bank, credit Shopify Clearing.

Here is one payout worked through for an Ontario seller charging 13% HST:

ItemAmountRecorded as
Product sales$1,800.00Sales
Shipping charged$100.00Shipping income
HST collected$247.00HST payable
Refund (one item plus HST)-$113.00Sales returns $100, HST payable $13
Processing fees-$62.40Merchant fees
Payout deposited$1,971.60Bank

After all four entries, the clearing account is back to zero, your sales are recorded at $1,800, your fees show up as an expense and your HST payable is exactly what you owe on these orders.

Getting Sales Tax Right on Shopify Orders

Shopify calculates tax on each order based on where the customer is, so a single payout can include 13% HST from Ontario, 5% GST from Alberta and 15% HST from Nova Scotia. Your books need to keep those apart, because your GST/HST return reports the tax you collected and the PST in some provinces is filed separately.

Use Shopify’s taxes report to split each period’s tax by province and record it to the right liability accounts. Sales to customers outside Canada are usually zero-rated. Our GST/HST guide for small business covers registration, rates and filing.

Other Channels and Payment Methods

Every place money is collected needs its own clearing account and its own reconciliation: Shopify Payments, PayPal, Shop Pay Installments, Amazon, Etsy and any wholesale invoices paid by e-transfer. Mixing channels in one account is the fastest way to end up with a balance nobody can explain.

Gift cards are another trap. Selling a gift card is not a sale yet; it is a liability until the card is redeemed, and sales tax applies when it is used, not when it is bought.

Shopify Bookkeeping Apps That Do the Heavy Lifting

Recording every order individually floods your accounting software and is hard to reconcile. Most sellers are better served by a connector that posts one summary entry per payout, already split into sales, tax by province, refunds and fees, into QuickBooks Online or Xero. You then only have to match each summary to its bank deposit.

Whichever tool you use, review the clearing account balance at every month end. A balance that keeps growing means something is not being recorded. Our guide to accounting software for small business in Canada covers how to connect your store, and inventory and cost of goods sold are covered in our ecommerce bookkeeping guide.

Want Your Store's Books Reconciled Every Month?

We set up clearing accounts, sales tax by province and payout reconciliations for Canadian online sellers, then keep them current every month. See our bookkeeping services or get in touch.

Book a consultation →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
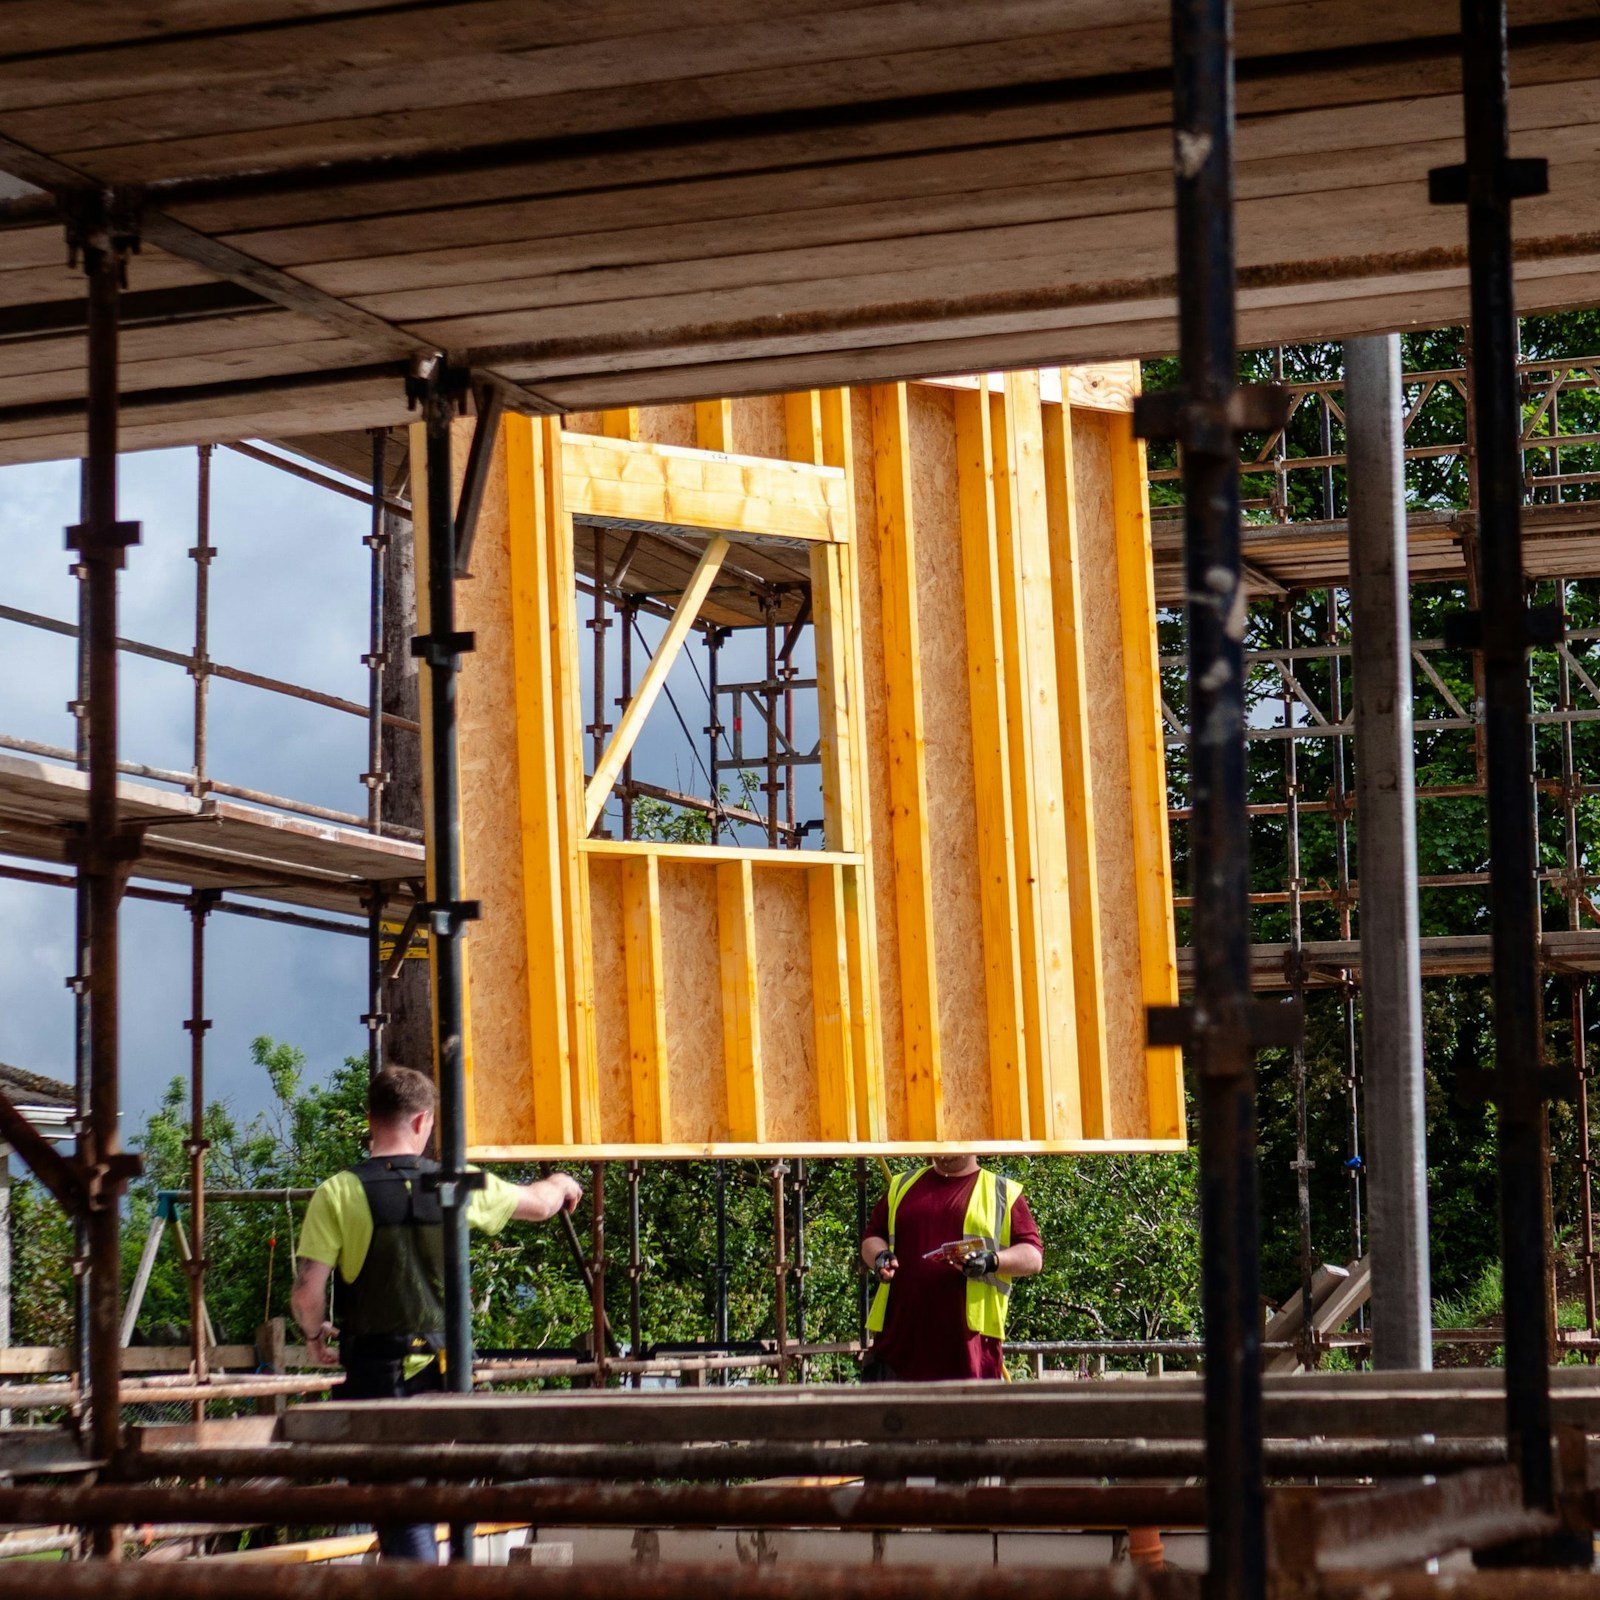
T5018 Slips in Canada: How Contractors Report Subcontractor Payments

Two construction workers lifting a framed wall into place on a building site

T5018 Slips in Canada: How Contractors Report Subcontractor Payments

Two construction workers lifting a framed wall into place on a building site
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

What Is a T5018 Slip?

If your business is mainly in construction and you pay subcontractors, the CRA expects you to report those payments every year on a T5018 Statement of Contract Payments. The slips let the CRA match what you paid against what each subcontractor reported as income, which is exactly why they matter: they are one of the main ways the CRA finds unreported construction income.

Most contractors only think about the T5018 when the deadline is close and they are digging through a year of supplier payments. This guide covers who has to file, which payments count, the deadline and how to set up your bookkeeping so the slips take minutes rather than days. It is part of our guide to construction bookkeeping in Canada.

Subcontractors building a wooden structure on a residential job site

Who Has to File T5018 Slips

The rule applies to individuals, partnerships, trusts and corporations whose primary source of business income is construction. The CRA treats construction as your primary source when more than 50% of your business income comes from construction activities.

Construction activities are broad. They include erecting, installing, altering, modifying, repairing, improving, demolishing, dismantling or removing any structure or part of one, from houses and commercial buildings to roads, bridges, dams and pipelines. General contractors, renovators, electricians, plumbers, HVAC companies, roofers, landscapers who build structures and site-preparation outfits are all commonly caught.

If you meet the test, you file for payments you make to Canadian-resident subcontractors for construction services, whether the work was done inside or outside Canada. The details are on the CRA’s T5018 slip page.

Which Payments Go on a T5018

Report the total you paid each subcontractor for construction services in the reporting period, as long as that total is more than $500. For the threshold you leave out GST/HST, but the amount you put on the slip in box 22 includes GST/HST and PST.

PaymentReport on a T5018?
Framing subcontractor paid $18,000 plus HSTYes, $20,340 including HST
Electrician who supplied labour and materialsYes, the full amount
Lumber yard, for materials onlyNo, goods only
Your own employeesNo, they get T4s
Subcontractor paid $450 in total for the yearNo, under the threshold

A slip is required whether the subcontractor is a sole proprietor, a partnership or a corporation. You report payments in the period you paid them, not when the work was invoiced.

T5018 Reporting Period and Deadline

You can report on a calendar-year basis or on your business’s fiscal period. Many contractors with a non-December year end choose the fiscal period so the slips line up with the year-end books.

The return, made up of the T5018 slips and the T5018 Summary, is due six months after the end of the reporting period. Using the calendar year, payments made in 2026 are due by 30 June 2027. With a 31 March fiscal year end, the slips are due by 30 September.

Put the date on the same calendar as your other filings. Our Canadian business tax filing calendar shows where it sits alongside your T2, GST/HST and payroll deadlines.

How to File T5018 Slips

You file the slips and the summary with the CRA, and you can also give each subcontractor a copy, which helps them reconcile their own income. Online filing through the CRA’s web forms or a payroll or accounting program is the norm, and electronic filing is mandatory if you file more than five slips.

Each slip needs the subcontractor’s name and address and their business number, or their social insurance number if they are an individual without one. Missing identification numbers are the most common reason the job drags on, so ask for them up front.

Late or missing slips attract penalties based on how many slips are involved and how late they are. A CRA review of a contractor who never filed T5018s also tends to widen into questions about whether those subcontractors were really employees.

Set Up Your Books So the Slips Write Themselves

The work is in the bookkeeping, not the form. A few habits make year end painless:

  • Onboard every subcontractor properly. Get their legal name, address, business number and GST/HST number before the first payment, and store them on the supplier record.
  • Flag subcontractors in your software. QuickBooks Online and Xero both let you mark suppliers or tag their bills so you can run a payments report for exactly that group.
  • Code labour and materials separately on bills, so materials-only suppliers never end up on a slip and mixed bills are reported in full.
  • Pay through the books. Cash and e-transfer payments that never get recorded are what makes a T5018 report wrong.

Our guide to accounting software for small business in Canada covers how to set this up. Getting the subcontractor’s GST/HST number also protects your input tax credits, which our GST/HST guide explains.

Want Your T5018s Done for You?

We keep construction clients’ supplier records, sales tax and subcontractor reports in order all year, so the T5018 is a quick review rather than a scramble. See our bookkeeping services or get in touch.

Book a consultation →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
Bookkeeping for Canadian Consultants & Professional Services

Two business partners reviewing a contract at a cafe table with a laptop

Bookkeeping for Canadian Consultants & Professional Services

Two business partners reviewing a contract at a cafe table with a laptop
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

The One-Client Problem: Personal Services Business Risk

Incorporating is normal for consultants, and for a substantial minority it creates an exposure most never hear about until an assessment arrives.

The personal services business rules apply where an individual provides services through a corporation and would reasonably be regarded as an employee of the client but for that corporation, where the worker is a specified shareholder and the company doesn’t employ more than five full-time employees.

Where they apply, the corporation loses the small business deduction and the general rate reduction, leaving it at the unreduced 28% federal rate, then pays an additional 5% federal tax on top, for 33% federally before provincial tax, and is denied deductions for almost everything except salary and benefits paid to the incorporated employee. Rent, equipment, software, professional fees, home office: all denied. Assessments typically cover every open year.

Consultants placed through agencies at a single client site, IT contractors on long engagements, and interim executives are the profiles most exposed. Our guide to the personal services business rules for consultants explains the test and how to reduce the risk, and the corporate tax mechanics are covered in our T2 corporate tax guide.

Consultants brainstorming over paper and a laptop

What you need to know

  • A corporation with one client and one worker is the classic personal services business profile: the most punitive classification in Canadian corporate tax.
  • Revenue belongs in the period it is earned, not invoiced or collected. Project work spanning a year end needs deliberate treatment.
  • A retainer is a liability until the work is done.
  • Rebilled disbursements are revenue and expense, not a netting exercise, and they usually carry GST/HST.
  • Utilisation and realisation matter more than revenue in a service business.

Reducing PSB Risk

There is no single fix, because the test looks at the whole relationship. But the factors that count are known, and several are within your control.

  • Multiple clients. The most effective single factor. Even a second meaningful client changes the picture substantially.
  • Your own tools and workspace. Working from your own premises with your own equipment, at least part of the time, weighs in your favour.
  • Control over how and when. Deliverable-based engagements beat hourly arrangements with set hours.
  • Financial risk. Fixed-price work where you absorb overruns, and the ability to profit from efficiency, are genuine indicators of business.
  • Right of substitution. A contract permitting you to send a qualified replacement, and the practical ability to do so, is strong evidence.
  • Your own insurance, marketing and business presence. Professional liability coverage, a website, business cards, active client development.

Contract language alone will not save an arrangement whose substance is employment: the CRA’s employee-or-self-employed tests look at the whole relationship, just as they do in Canadian small business payroll. It also isn’t irrelevant: a contract that reflects an independent arrangement supports the position. If your corporation has had one client for several years, get the arrangement reviewed properly.

Recognising Revenue on Projects and Retainers

Revenue is recognised when earned, which for services means as the work is performed. Three situations need care.

Work in progress at year end. Time spent and costs incurred on unbilled work represent revenue earned in the current year. Ignoring it understates income now and overstates it next year. Certain professions have had specific rules and transitional treatment for WIP; confirm the current position for your profession rather than applying a general rule.

Milestone projects. A fixed-fee engagement billed on milestones may have work performed well ahead of, or behind, the billing schedule. Where the amounts are material, recognise proportionate to work completed.

Multi-year contracts. A two-year retainer paid annually in advance is not two years of revenue this year.

For most small consultancies the difference between invoice-date recognition and properly earned revenue is immaterial and the simpler approach is fine. Once projects routinely span a year end, it stops being immaterial.

Retainers and Deposits

A retainer received before work is performed is deferred revenue, a liability, until you’ve earned it. The balance sheet mechanics are in small business accounting basics. Booking it as revenue on receipt inflates the current period and leaves the following one showing costs against nothing.

It matters more than it sounds. A consultancy collecting several large retainers in December looks highly profitable in a year it wasn’t, pays tax accordingly, and then delivers the work in a year with poor reported margins.

Where a retainer is refundable and held on account, the liability treatment is clear. Where it’s a non-refundable commitment fee, the analysis differs. Track the balance explicitly in either case.

Expenses and Disbursements

Consultants routinely incur costs on a client’s behalf (travel, subcontracted specialists, software licences, printing), and rebill them.

The correct treatment in most cases is gross: record the cost as an expense and the rebill as revenue. Netting them hides real activity, understates revenue in a way that can affect GST/HST registration timing, and makes margin analysis meaningless.

Rebilled disbursements generally carry GST/HST at your applicable rate, even where the original cost didn’t. An expense you incurred as principal and rebilled is part of your consideration for the service, not a pass-through, and the distinction between acting as principal and acting as agent determines the treatment. Getting this wrong systematically is a common finding on review.

Travel to a client site is business travel. Meals with clients remain 50% deductible. A home office used as the principal place of business follows the standard business-use-of-home rules set out in our sole proprietor tax guide.

What a Consulting Business Should Track

Service businesses have no inventory and few assets, so the meaningful numbers are about time and pricing.

  • Utilisation: billable hours as a share of available hours. Anything much above 70% for an owner-operator usually means business development has stopped.
  • Realisation: amount billed as a share of standard value of time spent. Persistent write-downs point to scoping or pricing problems, not effort problems.
  • Effective hourly rate: revenue by engagement divided by all hours spent including unbilled. Frequently reveals that the prestigious client is the least profitable one.
  • Revenue concentration: share from your largest client. Above 50% is a business risk; above 80% is also a PSB risk.
  • Days to collect, from invoice to payment.

Concentration is worth watching for both reasons at once, which makes it the most useful number on this list.

Working With Clients Outside Canada

Consultants reach international clients more easily than almost any other small business, and the tax treatment differs from domestic work in ways worth understanding before the first invoice.

GST/HST. Services supplied to a non-resident who is not registered in Canada are, in many cases, zero-rated: you charge nothing but continue to claim input tax credits on your costs. The rules are more specific than that summary suggests, with exceptions turning on where the service is performed, whether it relates to Canadian real property or goods, and whether the non-resident is in Canada when the service is supplied. Advisory work delivered remotely to a foreign company usually qualifies; a service connected to something physically in Canada often does not.

Two practical consequences follow. Foreign revenue still counts toward the $30,000 GST/HST registration threshold, because zero-rated supplies are taxable supplies at 0%. And a consultant with mostly foreign clients is typically in a refund position, which makes registration worthwhile even below the threshold and argues for filing more frequently than annually.

Withholding tax. Some countries require a payer to withhold tax on payments to foreign service providers. Where that happens, you receive less than you invoiced and may be able to claim a foreign tax credit against Canadian tax on the same income. Keep the withholding documentation; without it the credit is difficult to support. The relevant tax treaty often reduces or eliminates the withholding, but usually only if you provide the payer with the right residency certification before payment (for US clients, usually Form W-8BEN-E).

Currency. Invoice in a foreign currency and you carry exchange risk between invoice and payment. Record the receivable at the Bank of Canada rate on the invoice date and the difference on settlement as a foreign exchange gain or loss. Over a year of US-dollar invoicing this is a real number, and it belongs in your books rather than being absorbed into revenue.

Contracts worth having

A written engagement letter is worth more to a consultant than to almost any other small business, because the deliverable is intangible and disputes are therefore about memory. Define the scope, what is explicitly out of scope, the fee basis, what triggers additional fees, payment terms and interest on late payment, ownership of intellectual property, and how either party ends the engagement.

The scope and change-fee clauses do most of the work. Scope creep is the largest single cause of poor realisation in professional services, and it is far easier to raise a change fee against a written scope than to argue about what was originally agreed.

One Client and an Incorporated Business?

Our corporate tax filing team will review the arrangement against the PSB tests and tell you plainly where you stand, before the CRA does.

Book a review →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
Bookkeeping for Real Estate Agents and Investors in Canada

Hand holding house keys in front of a home entrance

Bookkeeping for Real Estate Agents and Investors in Canada

Hand holding house keys in front of a home entrance
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

Reporting Rental Income

Rental property is taxed on the same accrual basis as any business (explained in small business accounting basics), but with a set of rules that reward patience and punish the obvious moves.

Individuals report rental operations on the statement of real estate rentals filed with the T1, one per property or grouped where appropriate. Income is rent earned, not rent collected. Deductible costs include mortgage interest (never principal), property tax, insurance, utilities you pay, repairs and maintenance, property management, advertising for tenants, and reasonable travel to inspect or maintain. Our full list of rental property expenses you can deduct in Canada covers each one, plus repairs versus improvements.

Where you co-own, report according to ownership percentage, not who does the work or whose account the rent lands in. Allocating income to the lower-income spouse when title and capital contribution say otherwise is a straightforward reassessment.

Keep a separate bank account per property where practical. Rental files are among the most commonly reviewed, and a clean account is the difference between a short review and a long one.

Model house and keys on a desk

The essentials

  • CCA on a rental property cannot create or increase a rental loss, and claiming it can cost you more on sale than it saved.
  • A renovation that improves a property is capital, added to cost base, not deducted this year.
  • Converting a property between personal and rental use triggers a deemed disposition at fair market value.
  • Residential rent is exempt from GST/HST; commercial rent is taxable. The difference decides whether you recover tax on costs.
  • Ontario and BC agents may incorporate through a personal real estate corporation, with regulator-specific conditions.

The CCA Trap on Rental Property

You may claim capital cost allowance on a rental building (buildings acquired after 1987 sit in a class written off at 4% on a declining balance), but two rules make it a decision rather than an automatic claim.

First, CCA cannot create or increase a rental loss. If your rental operation is already at or below break-even, the claim is capped at the amount that brings income to nil.

Second, and more importantly: CCA claimed is recaptured on sale. Every dollar of depreciation you took comes back as fully taxable income in the year you sell, while the gain on the property itself is a capital gain taxed at the 50% inclusion rate. You have converted future capital gain treatment into future ordinary income.

For a property expected to appreciate, which is most Canadian residential real estate, claiming CCA is frequently a poor trade: a modest deduction now at your marginal rate, against a fully taxable recapture later, often in a year when the sale has already pushed you into the top bracket. Many advisers default to not claiming it on residential rentals for exactly this reason. Run the comparison rather than accepting either default.

Repairs vs Improvements on Rental Property

The same current-versus-capital question that runs through all business tax (see the sole proprietor tax guide), with higher stakes because the amounts are larger.

A repair restores the property to its previous condition and is deductible now: replacing broken windows, patching a roof, repainting between tenants, fixing a furnace.

An improvement betters the property beyond its original state, extends its life, or adapts it to a new use. It is capital, added to the adjusted cost base, and reduces your gain when you sell. Adding a bathroom, finishing a basement, replacing a roof entirely with better materials, or a full kitchen renovation are capital.

The line is blurry in the middle, and the CRA weighs factors including whether the work restored or enhanced, the value relative to the property, and whether it was part of acquiring the property in usable condition. Work done before a property is first rented is generally capital regardless of its nature: a point that catches many first-time investors who renovate before the first tenant and expect a deduction.

Change of Use Rules

Converting a property from personal use to rental, or the reverse, is treated as a deemed disposition at fair market value, followed by a reacquisition at that value. You may realise a taxable gain without selling anything or receiving any cash.

Elections exist that can defer this treatment in certain circumstances, with conditions attached, including limits on claiming CCA during the period covered. They must be filed properly and on time, and the interaction with the principal residence exemption is where the real value or damage sits.

Partial changes of use (renting out a basement suite, or using part of a home for business) raise the same issues on a proportionate basis, and can affect the principal residence exemption on that portion when you eventually sell. This is the most common way Canadians accidentally make part of their home taxable.

Any change of use is a point to get advice before acting, not after. The election deadlines are not forgiving.

Selling a Rental Property: Capital Gains and Recapture

On disposition you may face up to three amounts: a capital gain on the property’s appreciation, included in income at 50%; recapture of any CCA previously claimed, fully taxable; and, where applicable, a terminal loss if the remaining tax value exceeds proceeds.

Your adjusted cost base is what you paid plus capital improvements plus acquisition costs such as land transfer tax and legal fees. Selling costs (commission, legal, staging directly attributable to the sale) reduce proceeds. Keeping records of capital improvements over a long hold period is the most valuable habit for a property investor, because an improvement you can’t substantiate is one you can’t add to your cost base.

A separate and important question is whether the transaction is a capital gain at all. Property bought with the intention of resale, frequent flipping, or assignment sales can be treated as business income, fully taxable, with no capital gains treatment and no principal residence exemption. Canada also has specific rules deeming gains on residential property held for short periods to be business income, subject to limited exceptions. Intention at purchase matters, and so does your pattern of transactions.

GST/HST on Property

Long-term residential rent is exempt. You don’t charge tax, and you can’t recover tax on related costs: repairs, management fees, supplies all carry unrecoverable tax.

Commercial rent is taxable. Landlords of commercial property generally register, charge tax on rent, and recover tax on operating and capital costs: a much better position.

Short-term accommodation below certain duration thresholds is treated differently from long-term residential rent and can be taxable, which brings short-term rental operators into the registration question once they pass the small supplier threshold (see our GST/HST guide for small business).

New residential construction carries its own regime (self-supply rules, the new housing rebate, and the rental property rebate) that is specialised enough to need direct advice rather than general guidance.

Real Estate Agents and PRECs

Real estate agents are generally self-employed, receiving commission income with no tax withheld, which makes the instalment obligation and the set-aside discipline the defining financial habits of the job. Deductible costs include brokerage fees and desk fees, board and association dues, advertising and photography, vehicle costs on a logbook basis, client-related expenses within the usual limits, and licensing.

Ontario and British Columbia both permit agents to incorporate through a personal real estate corporation, subject to regulator conditions covering the corporation’s name, share ownership, and the requirement that the agent remain personally registered. Ontario’s rules are set out in O. Reg. 536/20 and administered by RECO; BC’s by the BC Financial Services Authority. Where permitted, a PREC offers the standard corporate advantages: the small business deduction on retained income (see our T2 corporate tax guide), deferral, and flexibility in how and when income is taken (see tax planning for owner-managers).

The threshold question is the same as for any incorporation: are you consistently leaving profit in the business? An agent spending everything earned gains administration and cost without the deferral benefit that justifies it. The provincial rules also change, so confirm current requirements with the regulator before setting one up.

Rental Portfolio or Commission Income?

Our bookkeeping service handles property-level bookkeeping, capital versus current decisions, and the CCA question properly, before you sell, not after.

Talk to us →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
Dental Bookkeeping and Accounting for Canadian Dental and Medical Practices

Modern dental office with chair and equipment

Dental Bookkeeping and Accounting for Canadian Dental and Medical Practices

Modern dental office with chair and equipment
Stay Ahead With Expert Bookkeeping Insights!
The Best Bookkeeping Tips Straight to Your Inbox!

Table of Contents

GST/HST Exempt Supplies in Dental and Medical Practices

Every other business in this series collects sales tax and claims back what it pays. Health practices mostly do neither, and that single fact reshapes the economics of running one.

Most services rendered by physicians and dentists to patients are exempt supplies for GST/HST purposes. Exempt is not the same as zero-rated. On a zero-rated supply you charge 0% but still recover input tax credits. On an exempt supply you charge nothing and recover nothing: the tax you pay on rent, equipment, lab fees, supplies and software is a cost.

For a practice paying $120,000 a year in taxable inputs in Ontario, that is roughly $15,600 in unrecoverable tax annually. It doesn’t appear as a line anyone reviews, because it’s embedded in every invoice.

The practical consequences follow directly. Budget in tax-inclusive terms. Compare equipment quotes tax-inclusive. And when weighing a lease against a purchase, remember that the tax on both is a real cost rather than a timing difference.

Dental treatment chair in a clinic

In short

  • Most health care services are GST/HST exempt, which means you don’t charge tax, and cannot recover the tax you pay on rent, equipment and supplies.
  • Practices with taxable or zero-rated elements may recover part of that tax, and most don’t claim what they’re entitled to.
  • Professional corporations are governed by your provincial regulator as well as the tax rules, and who may hold shares is restricted.
  • Associate arrangements structured as contracts carry genuine employee-reclassification and PSB risk.
  • Because tax on equipment isn’t recoverable, the real cost of a purchase is the tax-inclusive price, which changes lease-versus-buy arithmetic.

Mixed Practices and Partial Recovery

Few practices are purely exempt, and the exceptions are where recoverable money sits.

Certain medical devices and appliances are zero-rated rather than exempt. Orthodontic appliances are the most significant example, and the CRA has an established administrative approach allowing orthodontic practices to treat a portion of the fee as consideration for the zero-rated appliance, which in turn supports input tax credit claims on related inputs. Practices doing meaningful orthodontic work and not registered for GST/HST are frequently leaving a real annual amount unclaimed.

Purely cosmetic procedures performed for non-medical purposes are generally taxable rather than exempt. A practice with a significant cosmetic component may be required to register (the small supplier threshold rules are in our GST/HST guide for small business), and once registered gains partial input tax credit entitlement.

Other taxable elements appear in practices without anyone noticing: renting space to another practitioner, selling retail products, providing administrative services to an associate, or certain third-party reports and examinations not performed for treatment purposes.

Where a practice makes both exempt and taxable supplies, input tax credits are apportioned, and the allocation method must be fair, consistent and documented. This is technical, and it is worth a specific engagement rather than a general approach: the recovery usually exceeds the cost of the advice by a wide margin.

Dental and Medical Professional Corporations

Physicians and dentists in Ontario, Manitoba and British Columbia may incorporate, but a professional corporation sits under two sets of rules at once: the tax legislation, and the governing body for the profession in that province.

The regulator (the CPSO and RCDSO in Ontario, for example) typically dictates the corporate name, requires a certificate of authorisation to be obtained and renewed, restricts the business the corporation may carry on, and, most consequentially, governs who may hold shares. Ontario permits family members to hold certain non-voting shares in medical and dental professional corporations, a provision that does not exist for every regulated profession or in every province.

The tax advantages are the standard ones: the small business deduction on retained income, deferral, and the ability to time compensation (see our T2 corporate tax guide). What incorporation does not provide is protection from professional liability: malpractice exposure follows the practitioner regardless of structure. For the numbers and the decision itself, see our guide to dental professional corporations.

Where family members do hold shares, dividends to them are subject to the TOSI rules explained in our owner-manager tax planning guide, and professional corporations face a narrower set of exclusions than other businesses. Issuing shares without confirming the TOSI position is the most common planning error in this area.

Associates and Locums

Associate arrangements are usually structured as independent contractor relationships, with the associate billing the practice or retaining a percentage of billings. That structure is defensible when the substance supports it, and precarious when it doesn’t.

The same CRA control tests apply here as anywhere: who sets the schedule, who owns the equipment and the patient records, whether the associate can work elsewhere, who carries the financial risk. An associate working fixed hours set by the principal, using only the practice’s equipment, with no other engagements, looks like an employee.

An incorporated associate faces a second exposure: the personal services business rules. Reducing that exposure is covered in bookkeeping for consultants and professional services. A professional corporation with essentially one client (the practice) providing the services of its sole shareholder is squarely in the zone those rules target, and the consequences include loss of the small business deduction, an additional 5% federal tax, and denial of most deductions.

Locums and part-time associates working at a single location are the highest-risk profile. It is worth reviewing the arrangement properly rather than relying on the fact that it is common practice.

Dental Equipment and Leasehold Improvements

Practice equipment is capitalised and depreciated through capital cost allowance (the mechanics are in our sole proprietor tax guide), generally in the class covering furniture and equipment. Computer hardware and systems software fall into a faster class.

Leasehold improvements (the build-out of an operatory or clinic space) are their own class, written off over the term of the lease rather than at a declining-balance rate. Practices that invest heavily in a fit-out should confirm the lease term used, because a short initial term with renewal options produces a different result than a long one.

Because input tax on these purchases is largely unrecoverable in an exempt practice, the capitalised cost includes the tax. That raises the CCA base, which recovers part of the cost over time through deductions, but only part, and slowly.

Practice Cash Flow

Practice revenue arrives through several channels with different timing: patient payments at the point of service, insurance assignment with a lag, and provincial plan billings with their own cycle and their own adjustment and rejection patterns.

Reconcile each channel separately. Rejected and adjusted claims are the most commonly lost revenue in a practice, because a rejection that nobody follows up disappears rather than appearing as a bad debt. Track claims submitted against claims paid, monthly, and age the difference the way you would any receivable.

Buying Into or Acquiring a Practice

Practice transitions are among the largest transactions a health professional will undertake, and the structure is settled long before the money moves.

Asset purchase or share purchase. Buying assets means acquiring the equipment, leasehold improvements, patient records and goodwill, with cost allocated across them, which determines your future depreciation and is negotiated in the purchase agreement rather than decided afterwards. Buying shares means acquiring the corporation whole, including its history and any liabilities in it, and is generally preferred by the vendor because it may access the lifetime capital gains exemption.

The allocation of purchase price in an asset deal deserves real attention on both sides, because it is zero-sum: amounts allocated to depreciable equipment give the buyer faster write-offs and the vendor recapture, while amounts allocated to goodwill are treated differently again. It is a negotiable term with a measurable value, and it is frequently signed without anyone modelling it.

Goodwill typically represents the largest part of a practice’s value and is depreciated slowly, so the after-tax cost of a purchase is higher than the headline price suggests. Factor that into financing rather than assuming the purchase price is deductible over a few years.

Patient records carry obligations beyond their commercial value. Provincial privacy legislation and your regulator both govern their transfer and retention, and the retention period for clinical records commonly exceeds the CRA’s six years by a wide margin. Confirm what you are required to keep and for how long before agreeing who holds what.

Buy-ins and partial interests

Buying a partial interest in an existing practice introduces a further question: are you acquiring shares of the professional corporation, an interest in a partnership, or a cost-sharing arrangement with separate practices under one roof? These are different structures with different tax, liability and exit consequences, and the informal version (everyone shares the rent and splits the staff) is the one most likely to produce a dispute when someone leaves.

Whatever the structure, agree the exit terms at the start. Valuation method, notice period, what happens to patient records, restrictive covenants and how a departing party is paid out are all far easier to settle while everyone is optimistic. A practice agreement without an exit clause is the most common source of expensive disagreement in this sector.

Practice Books That Account for Exempt Supplies Properly?

Our bookkeeping service works with dental and medical practices on GST/HST recovery, professional corporation structure, and associate arrangements.

Talk to us →

Related articles

image

Personal Services Business: The Tax Trap for Incorporated Consultants

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Rental Property Expenses in Canada: What You Can Deduct on Form T776

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…
image

Should a Dentist Incorporate? Dental Professional Corporations in Ontario

Stay Ahead With Expert Bookkeeping Insights! The Best Bookkeeping Tips Straight to Your Inbox! Table…